Taking Money Out of Your Company This Christmas? Don’t Get Caught by Division 7A
Robert
November 19, 2026
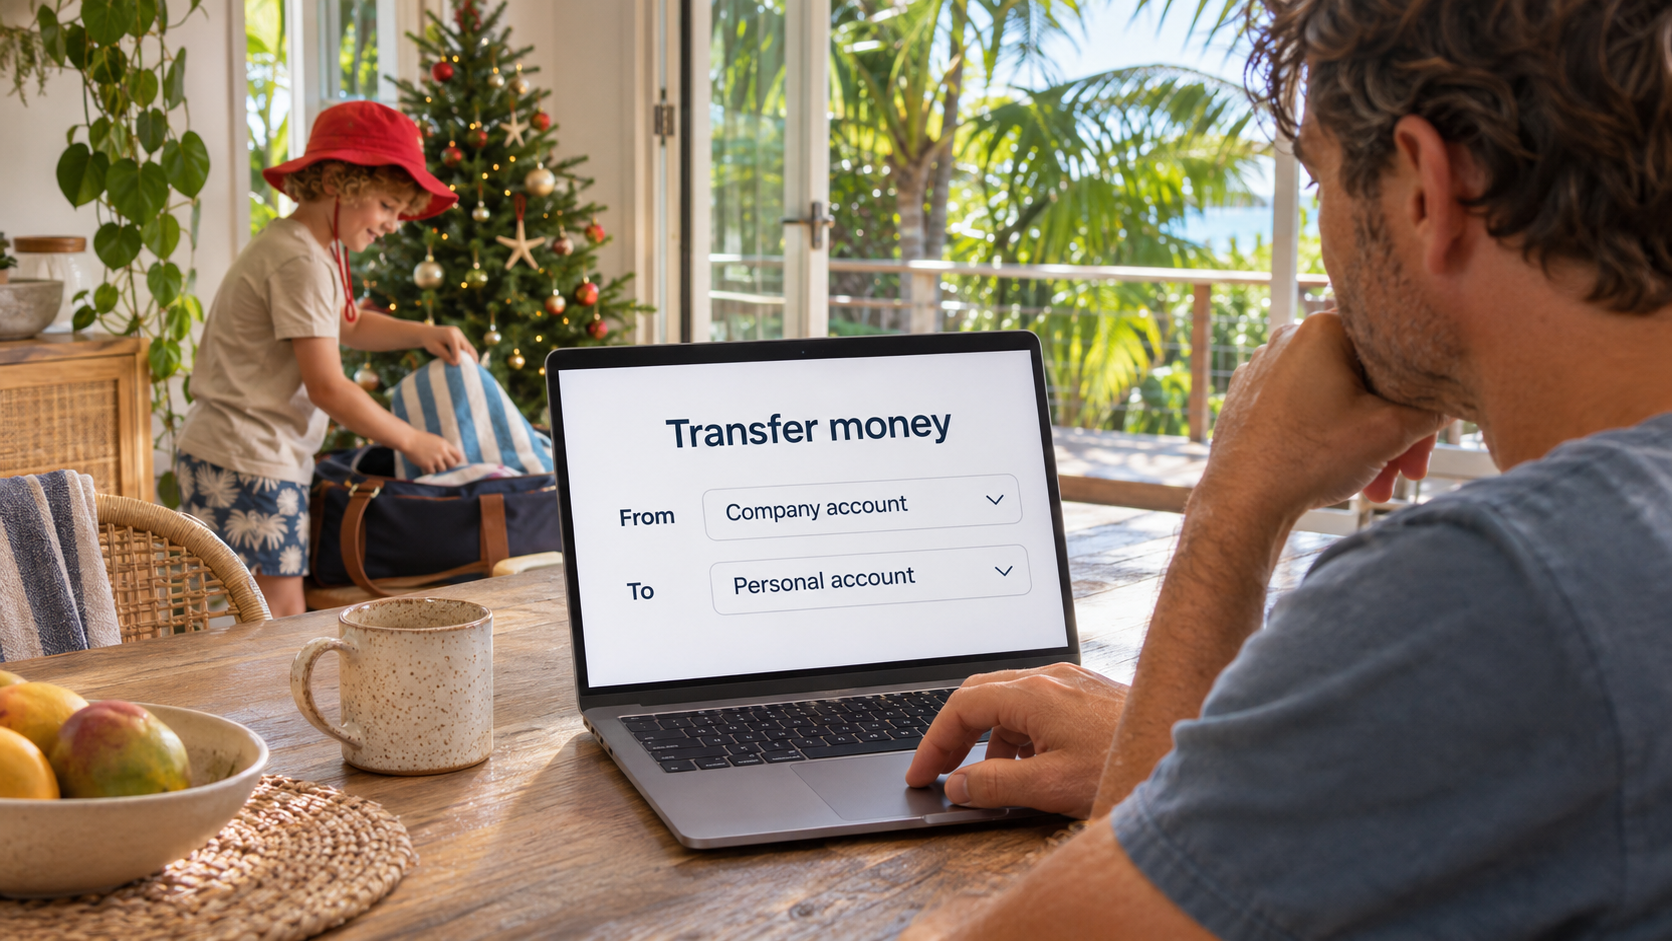
It’s that time of year. The business has had a decent run, the holidays are coming, and it’s tempting to transfer a bit from the company account to cover presents, a trip away or the mortgage. Plenty of company owners do it without a second thought.
The catch is that the ATO doesn’t see company money as your money, even if you own 100% of the shares. If cash leaves the company and goes to you (or your family) without being properly treated as wages, a dividend or a formal loan, Division 7A can treat it as an unfranked dividend. That means it gets taxed at your marginal rate with no credit for the tax the company has already paid.
What Division 7A actually catches
Division 7A applies to private companies. It can be triggered when the company:
- Pays money to a shareholder or an associate (spouse, family member, related trust) — for example, paying a personal credit card or private school fees from the business account.
- Lends money to a shareholder or associate — the classic “director’s loan” that builds up through the year.
- Forgives a debt owed by a shareholder or associate.
- Lets you use company assets privately — such as a holiday house or boat owned by the company — without paying market value for it.
In Xero or MYOB this usually shows up as a growing debit balance in a “Director’s Loan” or “Shareholder Loan” account. If that balance is still sitting there at the end of the year, it needs attention.
The timing that matters
You don’t have to fix a loan the moment it happens. The key deadline is the earlier of the due date or actual lodgment date of the company’s tax return for the year the loan was made. By then, the amount needs to be either:
- repaid in full (and not simply re-borrowed straight away), or
- put under a complying Division 7A loan agreement in writing.
Miss that date and the whole amount can be treated as a deemed dividend, up to the company’s distributable surplus.
Complying loan agreements: the 2026–27 numbers
A complying loan agreement lets you keep the money as a genuine loan. The main requirements are:
- A written agreement in place before the company’s lodgment day.
- A maximum term of 7 years (unsecured) or 25 years if secured by a registered mortgage over real property.
- Interest charged at least at the ATO benchmark rate, which is 8.77% for the 2026–27 income year (up from 8.37% in 2025–26).
- Minimum yearly repayments of principal and interest made by 30 June each year.
That interest is income to the company, and the minimum repayment has to come from somewhere, which is often a dividend or extra salary. So a Division 7A loan isn’t free money; it’s a structured way to defer the tax, not avoid it.
Better ways to pay yourself
Most owners are better off planning their drawings from the start:
- Wages or director’s fees — run through payroll with PAYG withholding and super. Tax deductible to the company and the cleanest option for regular personal spending.
- Franked dividends — paid from after-tax profits, with franking credits for the company tax already paid. Useful once the company has retained profits.
- A planned complying loan — for a one-off larger amount, with the agreement and repayment plan sorted before year-end.
The right mix depends on your personal tax position, how much profit the company has kept, and your cash flow. Getting it right can save a lot compared with tidying it up after the fact.
Quick holiday checklist for company owners
- Check your director’s loan balance in your accounting software now.
- Avoid paying personal bills straight from the company account.
- If you’ve already drawn money this year, talk to us before 30 June about how to treat it.
- Have an existing Division 7A loan? Make sure this year’s minimum repayment is in your diary for June.
Need a hand?
Brick Road Accounting helps company owners across the Gold Coast and Brisbane, from Ormeau to Pimpama, Coomera and beyond, set up a sensible way to pay themselves and stay on the right side of Division 7A. If your director’s loan account has been creeping up, get in touch and we’ll sort out a plan before it becomes a tax bill.
Related: ATO Loses Key Division 7A Case – What It Means for You
This article is general information only and doesn’t take your personal circumstances into account. Please get advice before acting on it.
Dont Hesitate To Contact Us
Have a question about your tax, accounting, or business needs? Our team is here to help. Get in touch today.